Where the East London market sits today
Value buying in Beacon Bay, Nahoon, Vincent and Bonnie Doon, steady rental demand from industry and government, and renewed interest in beachfront sectional title.
Prices in East London do not move in isolation. They respond to who is buying, what stock is available and how much finance costs at the time. Understanding those three levers is usually more useful than tracking a single headline growth percentage, because it tells you whether the demand behind a price is durable or temporary.
What drives house prices in East London
Several local forces do most of the work in setting values here:
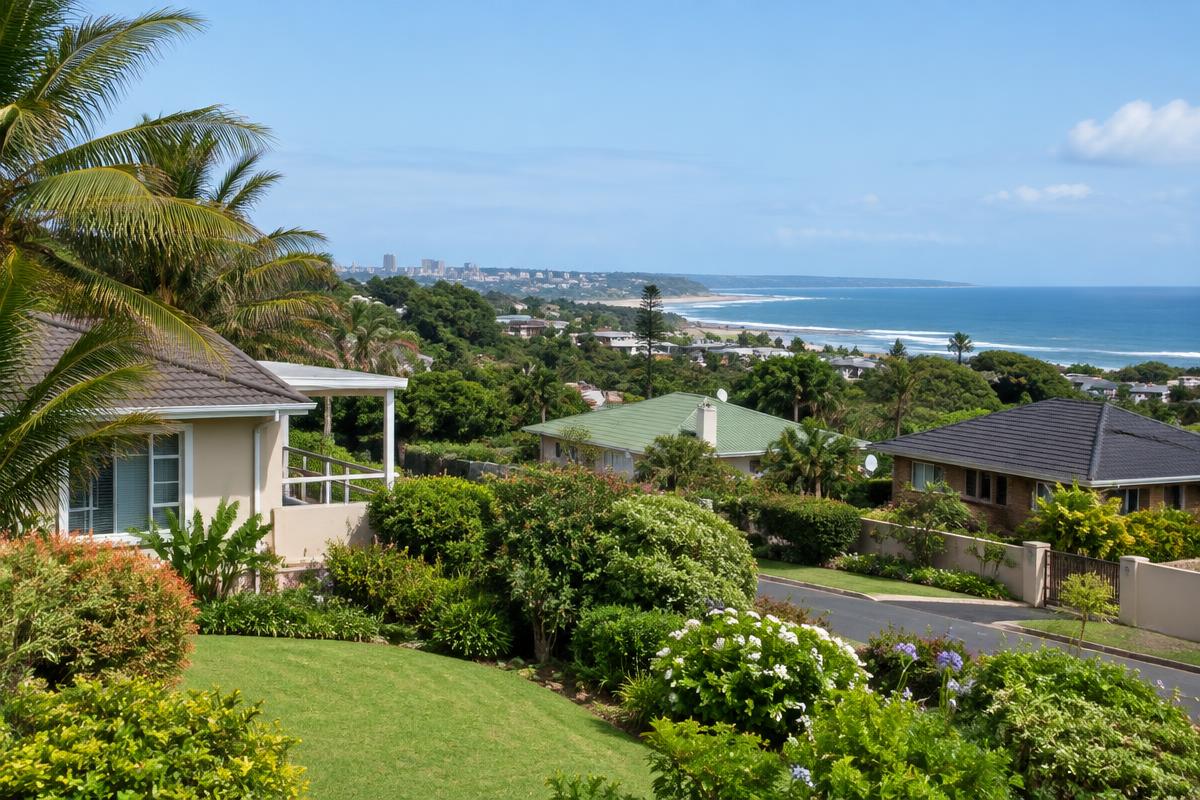
- Buyer demand and who is moving in — Beachfront apartments and leafy suburbs remain well priced compared with other coastal cities.
- Supply of well-located stock: limited land, protected areas or slow release of new developments keep values firm, while a wave of new units can flatten growth for a season
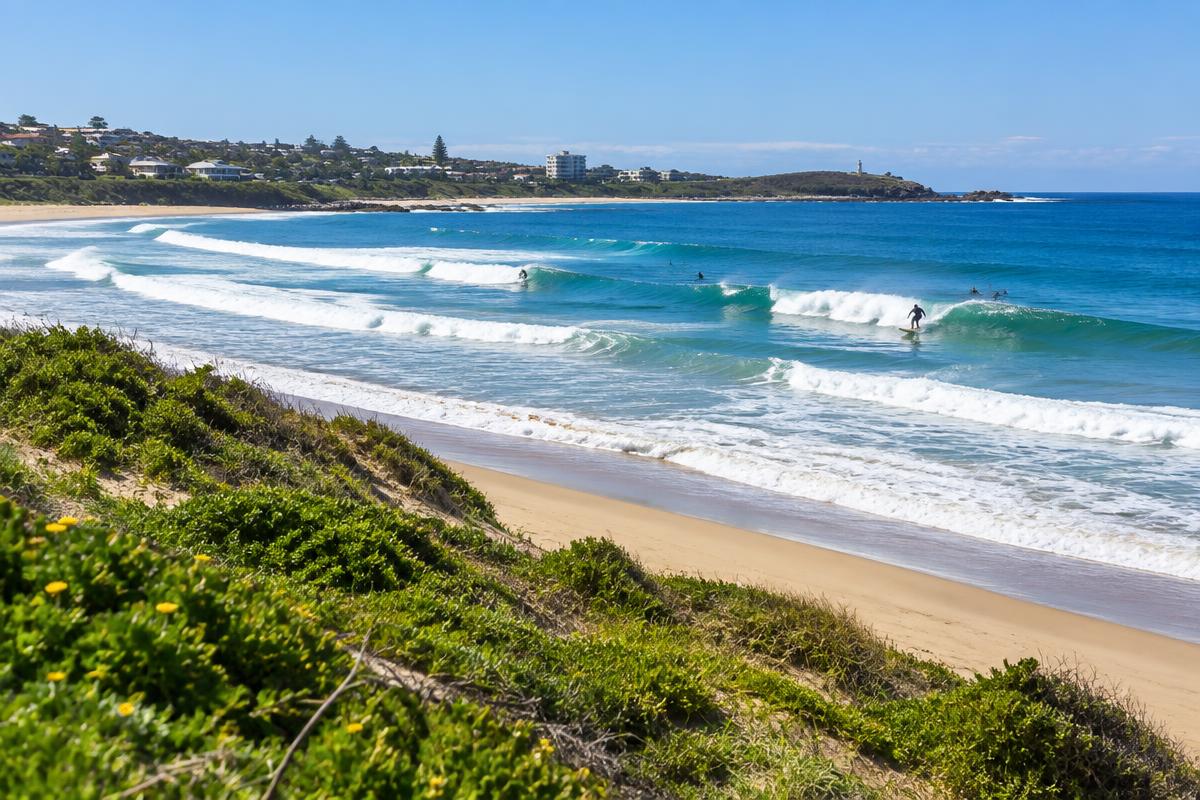
- Lifestyle appeal: Warm swimming beaches, easy commutes, good schools, a regional airport and a slower pace than the big metros.
- Interest rates and affordability — every repo rate change alters how much a qualifying buyer can borrow, which feeds directly into offer prices
- Infrastructure, safety and municipal service delivery, which strongly influence which suburbs of East London outperform the town average
Why property here is considered a good buy
- Coastal property at well below national coastal averages
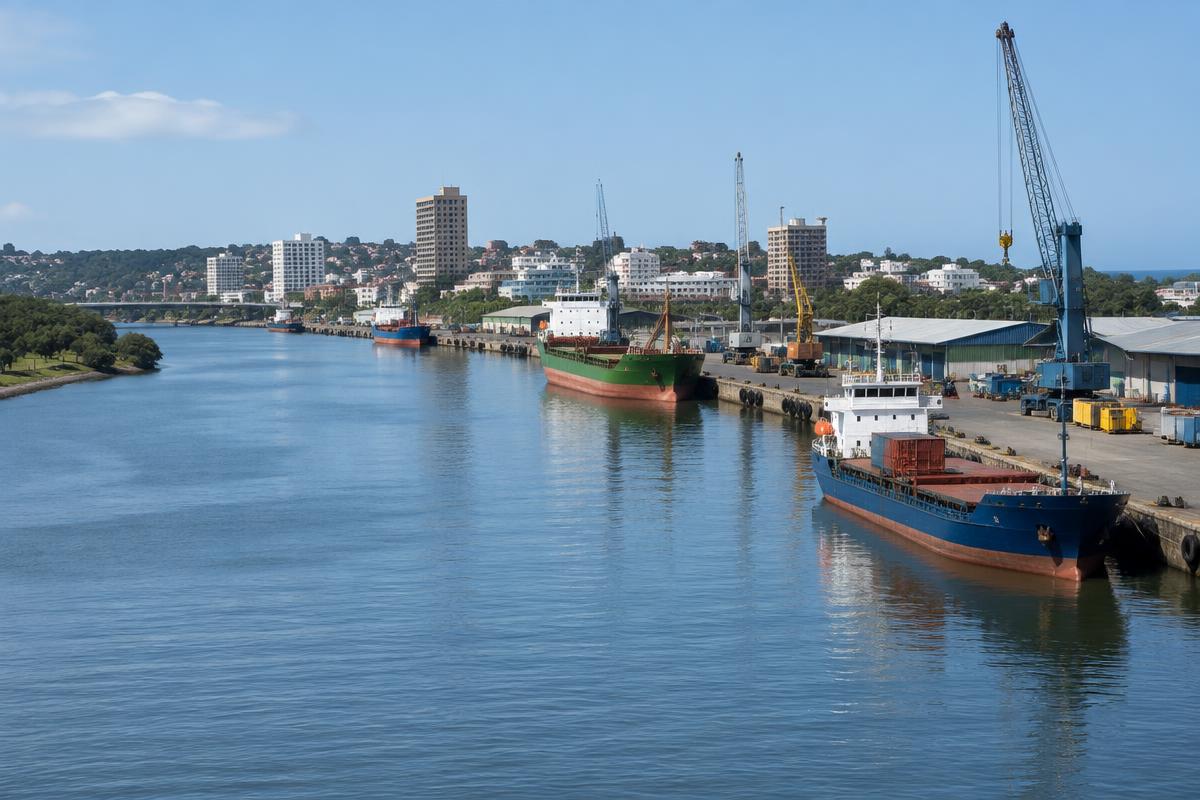
- Automotive and industrial employment supports rentals
- Strong demand for family homes near good schools
- Holiday and short-let potential on the beachfront
How to read price growth as a buyer
Average price growth across East London hides a lot. Two homes on the same street can perform very differently depending on plot size, condition, security, access to schools and whether the property suits the dominant buyer in the area. Before you make an offer, ask your agent and your originator for recent transfer prices of genuinely comparable homes, not asking prices.
Also weigh holding costs. Rates, levies, insurance and maintenance affect your real return as much as price growth does. A slightly cheaper home with high levies can cost more over five years than a better-located property bought at full price.
Financing a purchase in East London
The strongest position in any market is a buyer who already knows what they qualify for. A Gateway originator submits one application to multiple South African banks, then compares the interest rate, loan-to-value and term each lender offers on your East London purchase. That comparison is often worth more than negotiating a small discount on the purchase price, because the rate applies for the full life of the bond.